

The organization
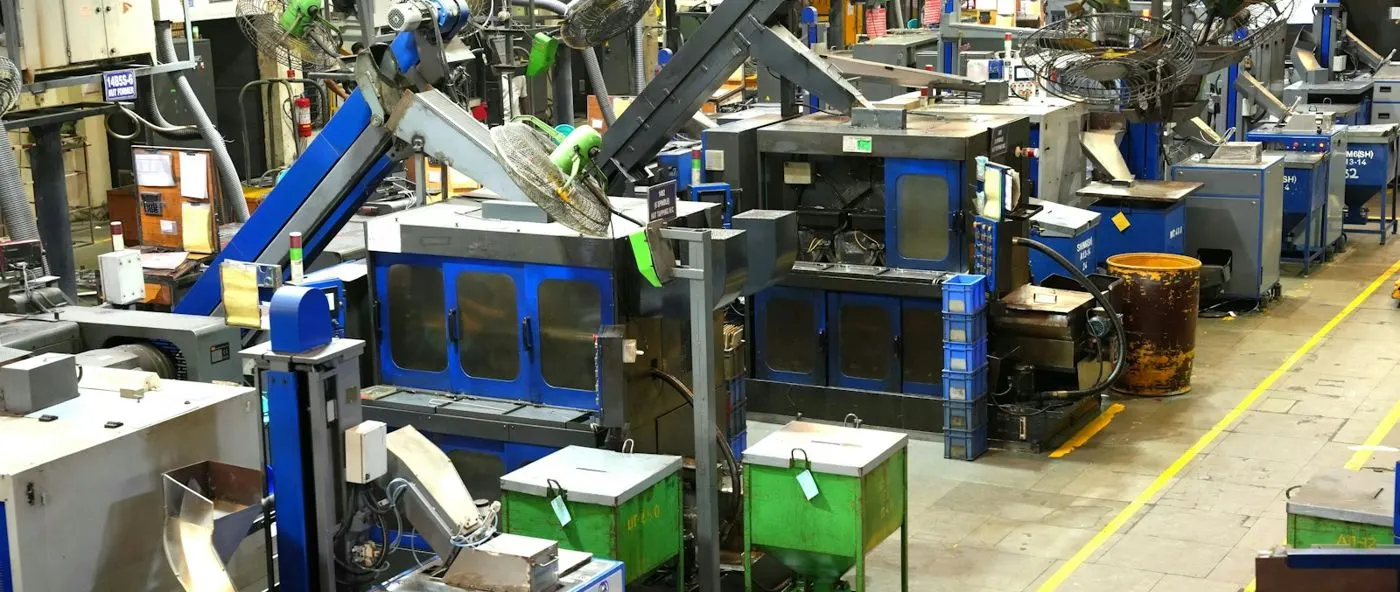
A mid-sized manufacturer in India runs three plants and a head office, with plant and machinery, buildings, vehicles, furniture and IT equipment on its fixed asset register.
Like every Indian company, it depreciates assets under Schedule II of the Companies Act for its books and by block of assets under the Income-tax Act for its return, and its auditors expect a physical verification of fixed assets.
The challenge
The register is a spreadsheet, and each depreciation basis has its own workbook. Physical verification is a printed list and a team walking the plants in March.
- Book and tax workbooks drift apart as additions and disposals are keyed twice.
- Additions put to use for fewer than 180 days in the year need half-rate tax depreciation, worked out by hand.
- The monthly charge is a formula nobody can explain, and double-shift months are missed.
- A sale gives a profit in one workbook and a smaller block in the other, and the two get mixed up.
- Verification lists come back with ticks and notes that take weeks to reconcile.
- Auditors ask why the two books differ, and for proof of verification that is hard to produce.
Why every Indian company keeps two depreciation books
The Companies Act and the Income-tax Act answer different questions about the same assets, so they give different figures, and both have to be kept.
| Companies Act, 2013 (Schedule II) | Income-tax Act, 1961 (section 32) | |
|---|---|---|
| Unit | Each asset, and each significant component | A block of assets with the same rate |
| Method | Straight line over the useful life (written-down value is allowed) | Written-down value at the block rate |
| Life or rate | Useful lives from Part C: 30 years for factory buildings, 15 for plant and machinery, 25 for continuous process plant | Rates from Appendix I: 10% for buildings, 15% for plant and machinery, 40% for computers, 25% for intangibles |
| Residual value | Normally up to 5% of cost | None: the block runs towards zero |
| Charged | Every month, from the date put to use | Once a year, for the whole block |
| Extra shifts | +50% for a double shift, +100% for triple; none for assets marked NESD | No such rule |
| Late additions | Charged for the days in use | Half the rate if put to use for fewer than 180 days |
| A sale | A profit or loss against the carrying amount | The price comes off the block; an excess is a gain under section 50 |
| Impairment, leases, estimates | Ind AS 36, Ind AS 116 and a prospective change of estimate | Not recognized; lease rent is an expense |
Take one machine costing ₹10 lakh. The Companies Act book charges ₹63,333 a year for fifteen years. The Income-tax book claims ₹1,50,000 in year one and ₹1,27,500 in year two. Neither is wrong, and the gap between them is what deferred tax is measured on.
How it is set up in Asset Infinity
The company keeps one fixed asset register in Asset Infinity, runs both depreciation bases from it and verifies assets with the mobile app.
Schedule II book depreciation
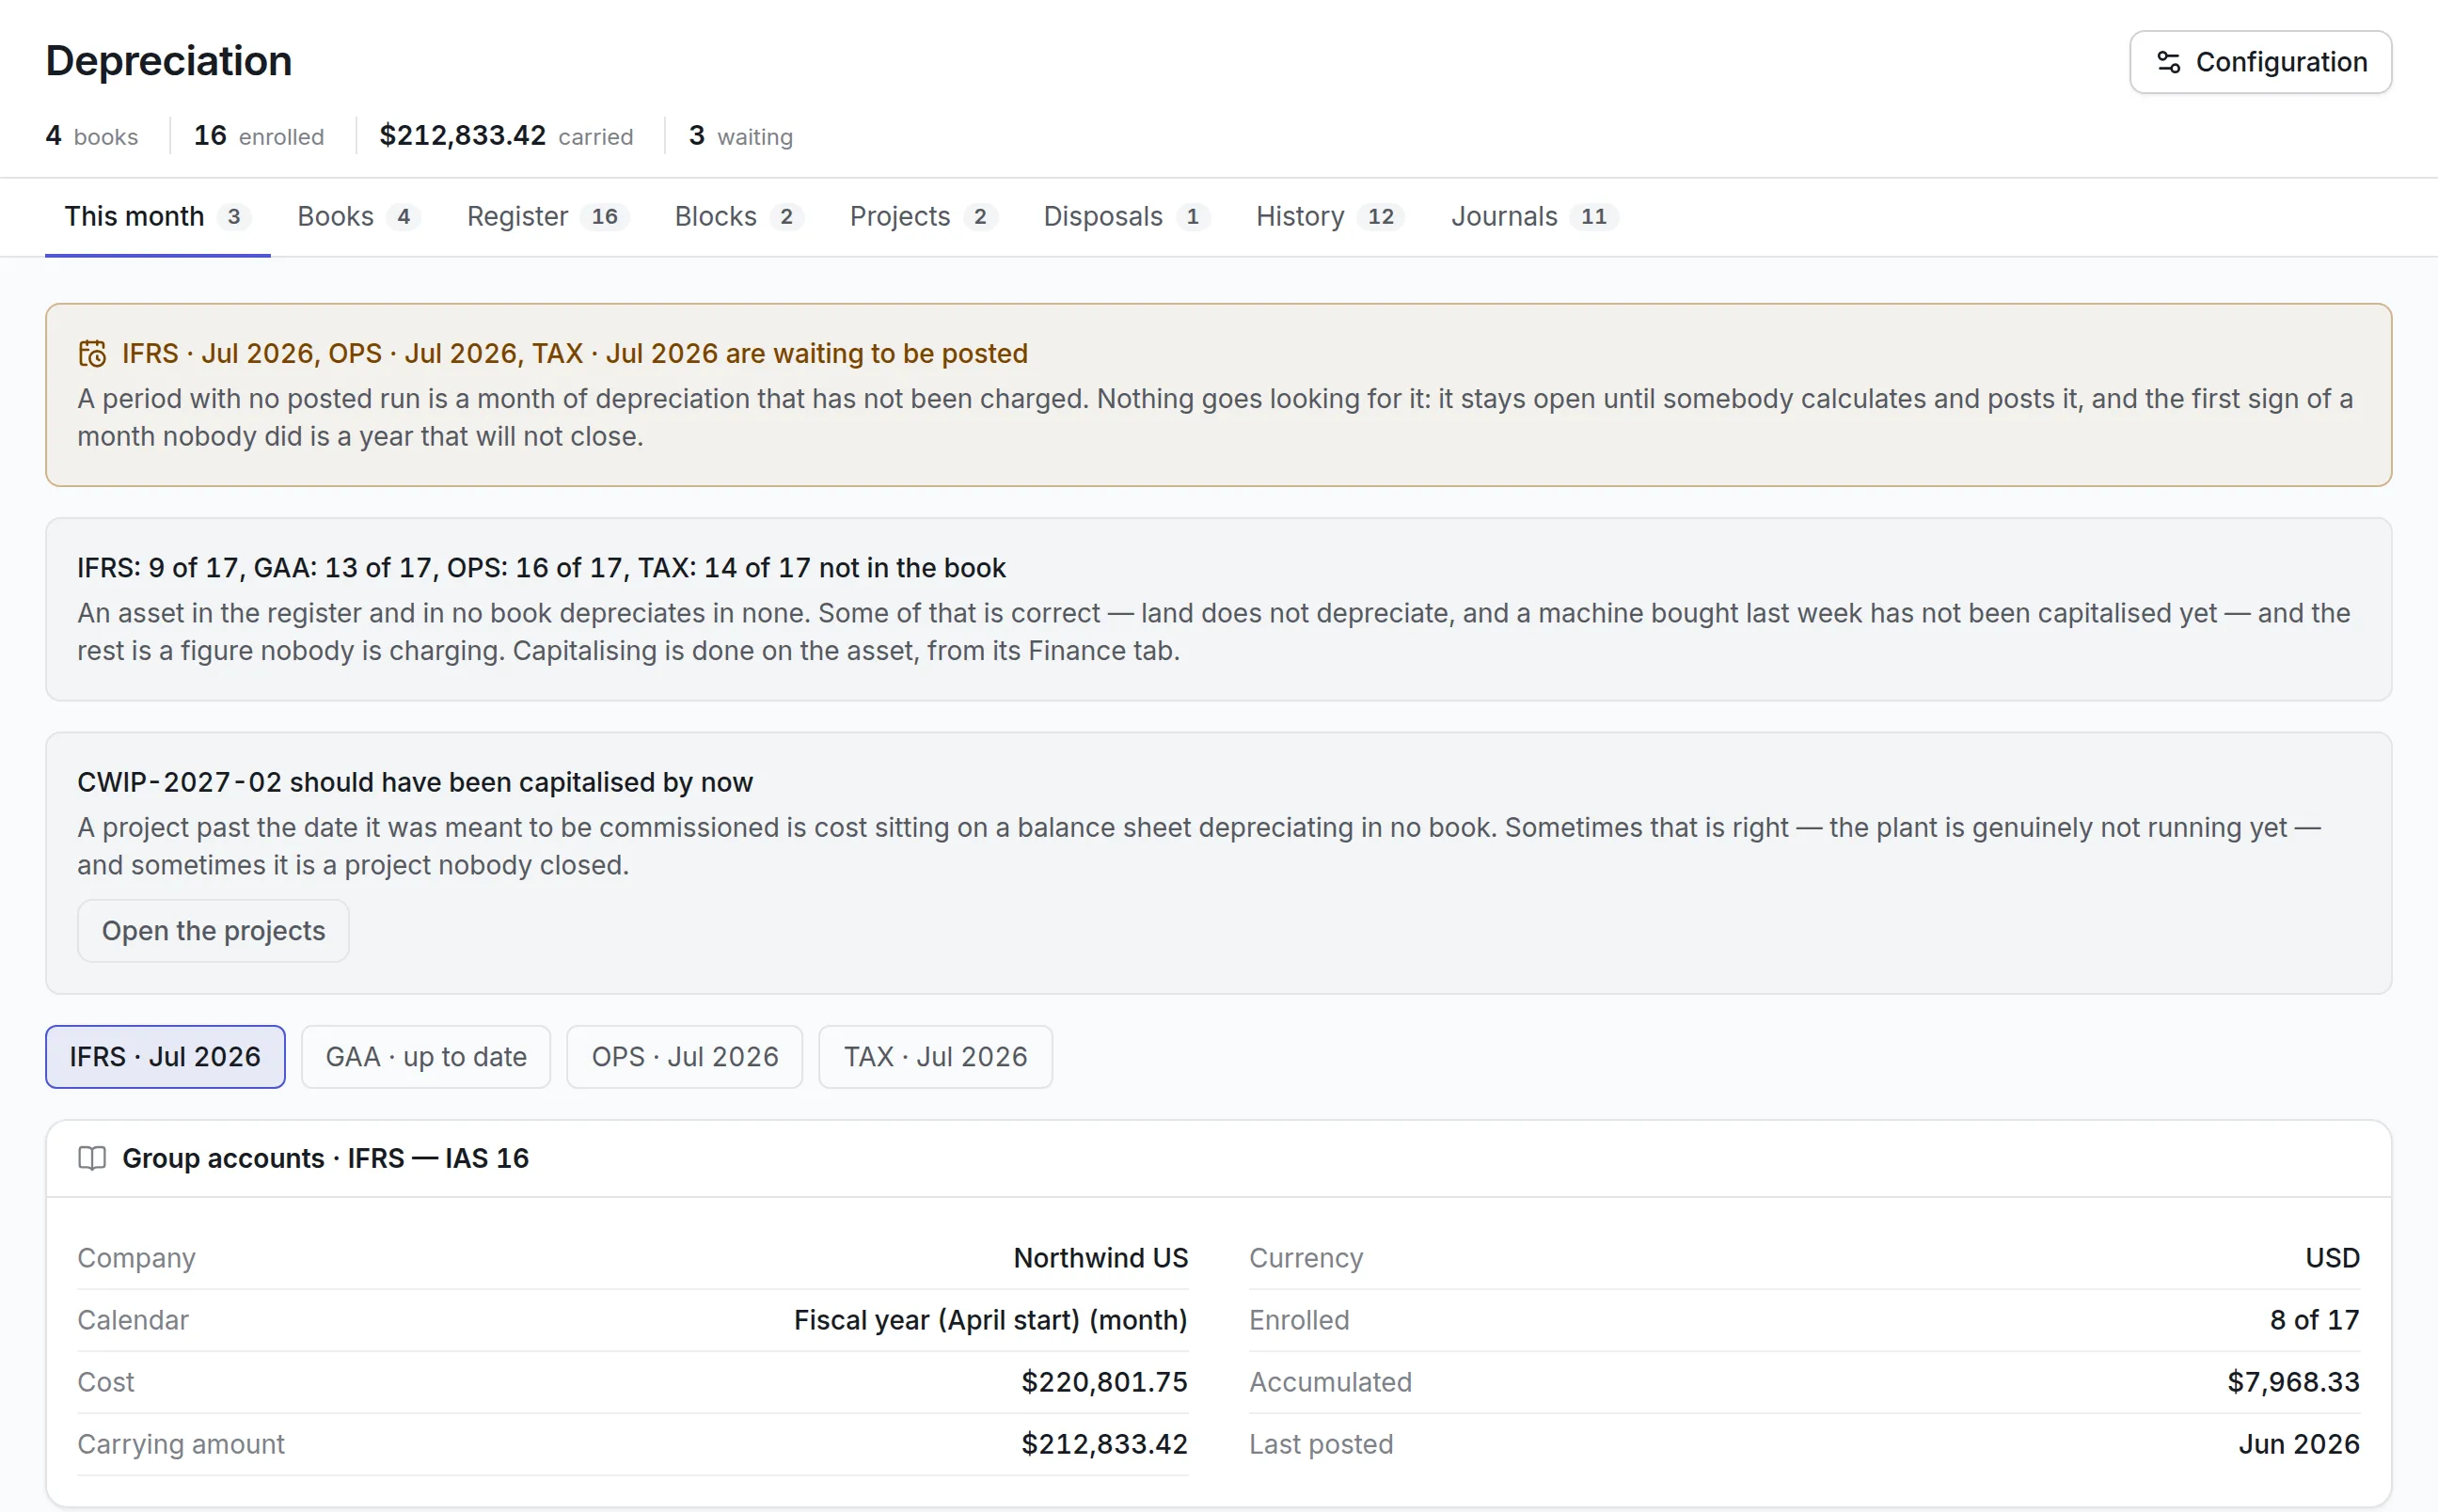
Each asset carries its Schedule II class, useful life and residual value, and book depreciation is calculated per asset every month. Plant on an hour meter gets Schedule II’s extra shift charge for the months it ran double or triple shift, and continuous process plant gets none. (Finance)
Income-tax blocks alongside
The same assets sit in Income-tax blocks at their Appendix I rates. Each year the block’s opening written-down value, additions and sale proceeds are worked out, with the 180-day rule applied to each addition. (Finance)
Components, leases and projects
A production line can be carried as components with their own lives, a leased office as a right-of-use asset in the Companies Act book only, and a line under construction as a project that is not depreciated until it is capitalized. (Finance)
Physical verification rounds
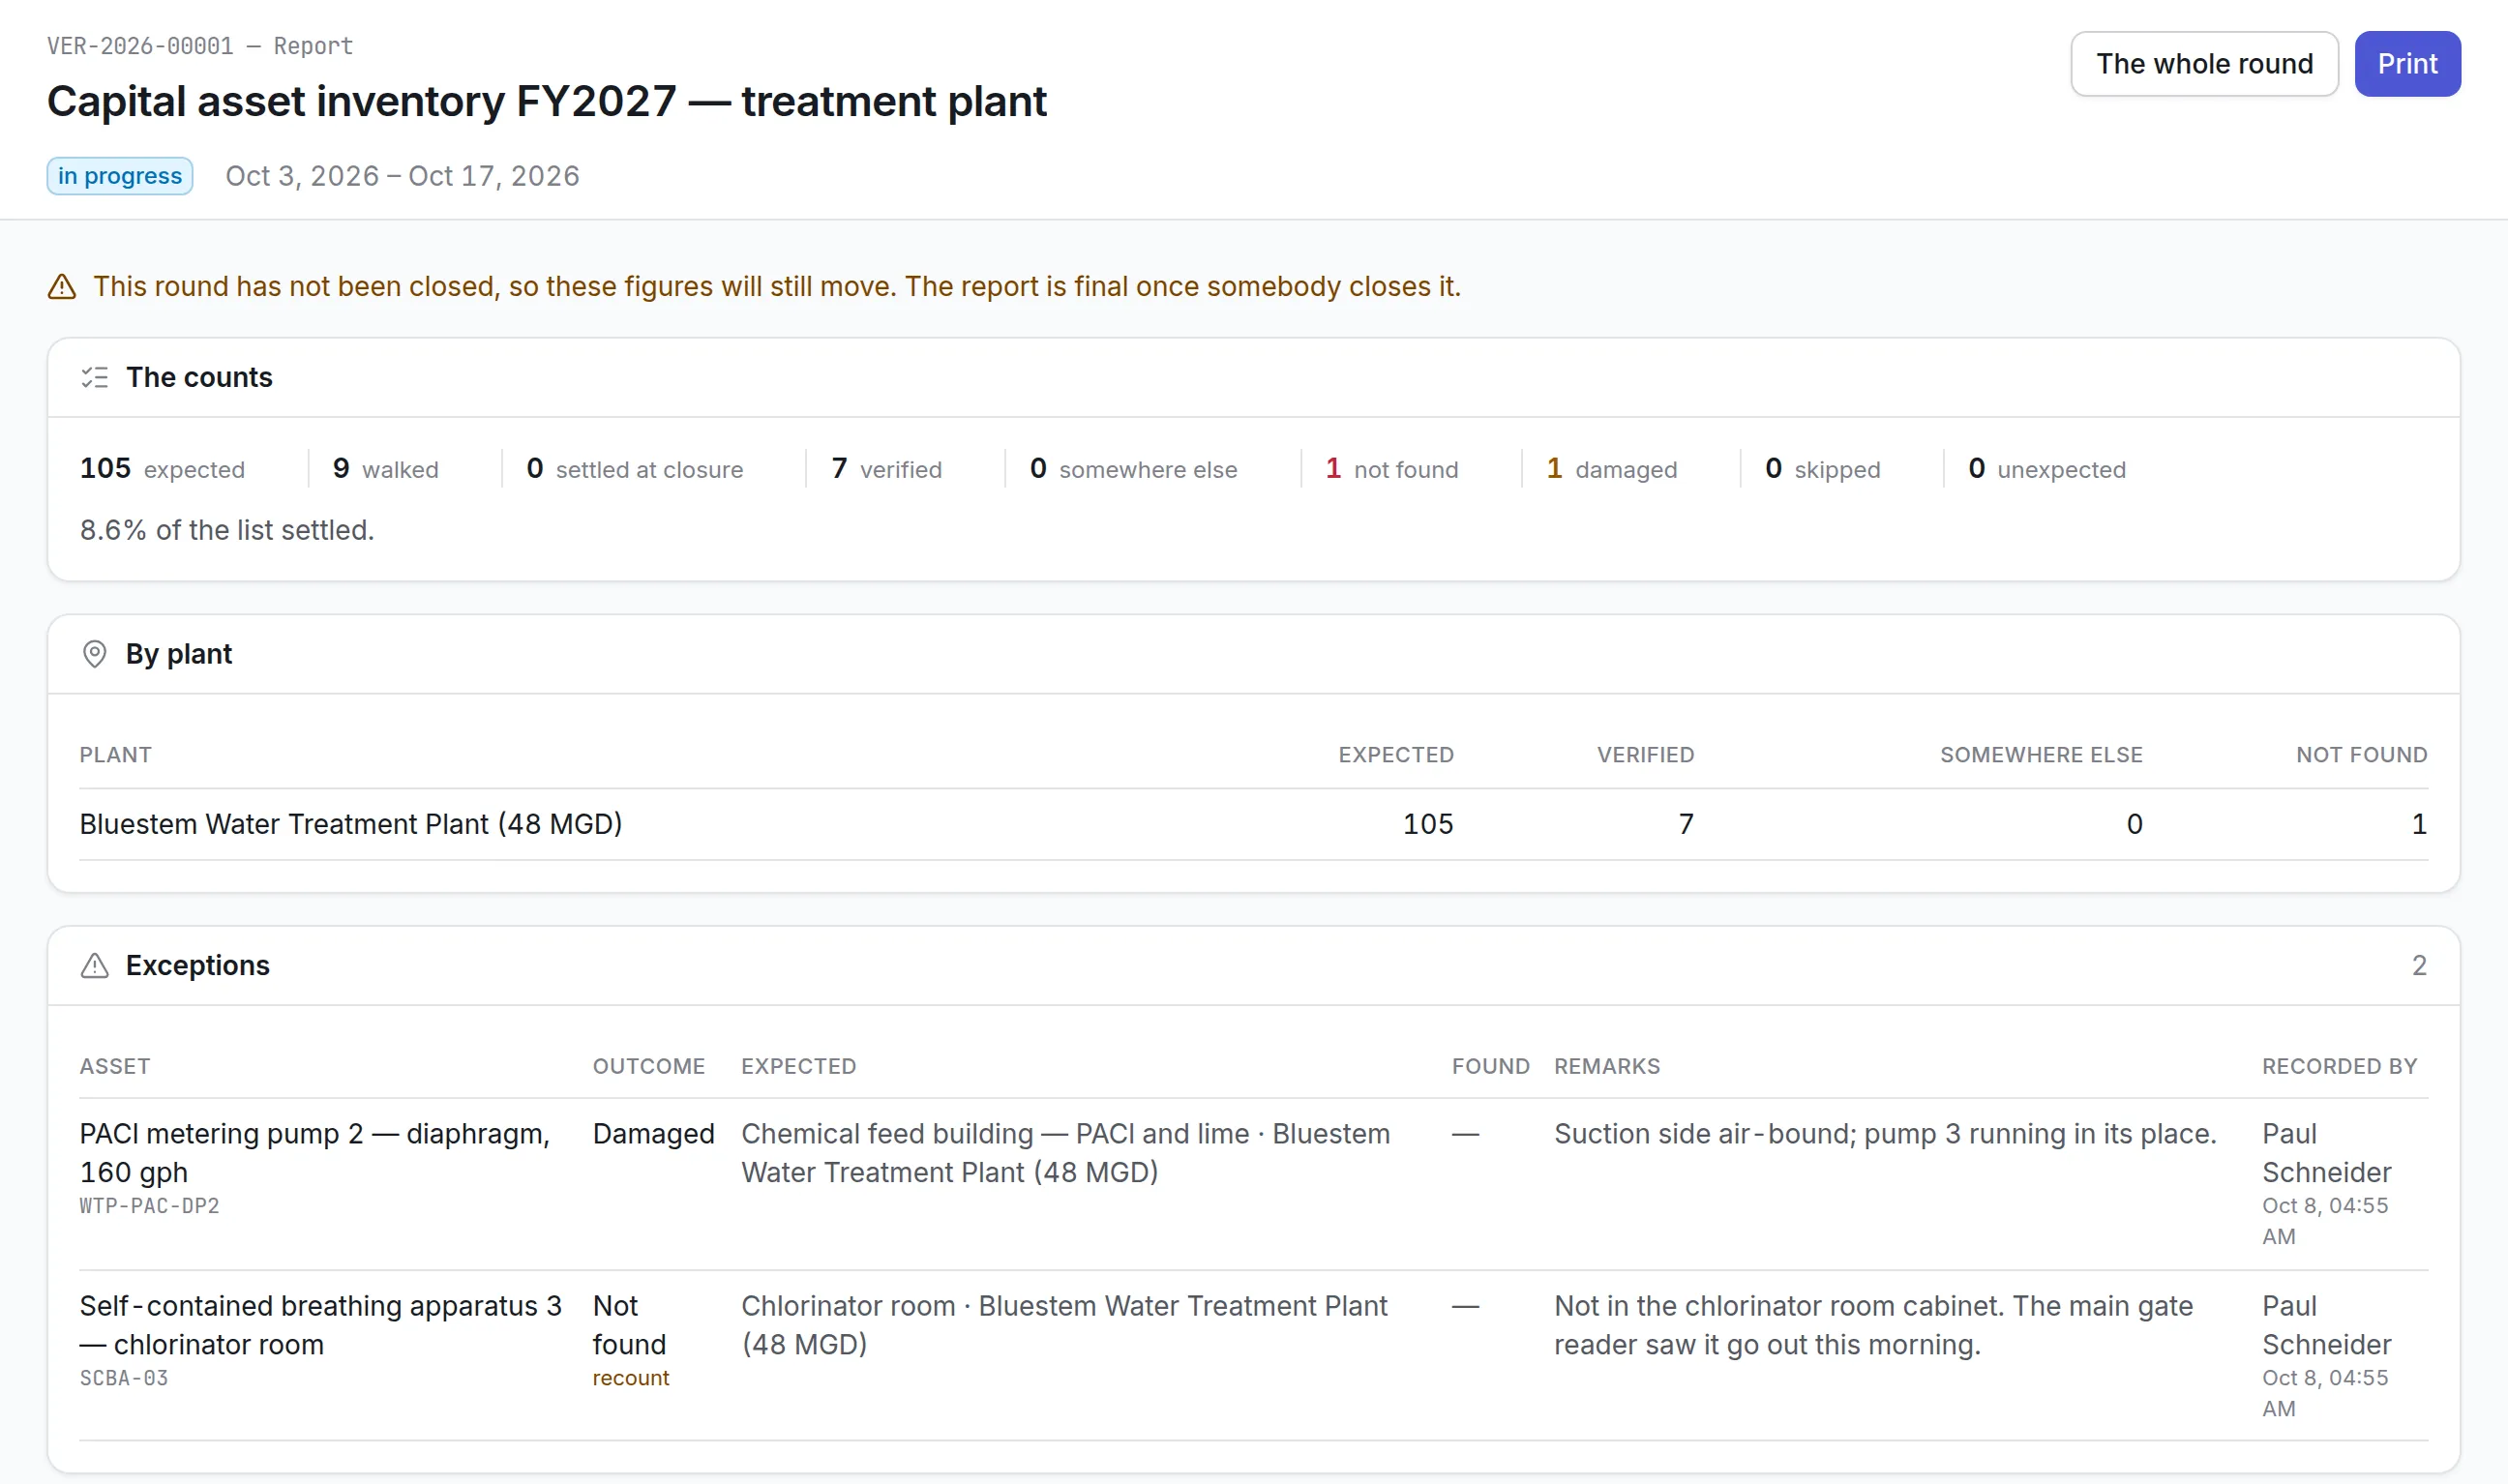
Auditors scan asset labels in the mobile app and mark each one verified, moved, not found or damaged, with photos where needed. (Assets)
Disposals and journals
A sale or write-off is recorded once, and each book draws its own result: a gain or loss in the Companies Act book, a reduced block in the Income-tax book. Depreciation and disposal journals are sent to the accounting system or downloaded. (Finance)
How it works day to day
Here is how the fixed asset year runs, from a new addition to the year-end close.
- Accounts executive: capitalizes an addition. A new CNC machine is added with its cost, the date it was put to use, its Schedule II useful life, residual value and Income-tax block.
- Plant admin: labels and places it. The machine gets a QR label, a location and a custodian, so it can be found and verified later.
- Fixed asset accountant: calculates the month. The Companies Act run is calculated, with the assets it could not charge listed first and every charge showing its working.
- Finance controller: posts it. Only the controller can post or reverse a month, so preparing and approving stay with different people.
- Tax manager: computes the blocks. Once a year, each Income-tax block is worked out from its opening value, additions at full or half rate and sale proceeds.
- Finance manager: opens the verification round. Before year end, a verification round is opened for each plant and assigned to its audit team.
- Verification team: scans assets on the floor. Team members scan each label and mark the asset verified, moved, not found or damaged, adding a photo for damaged items.
- Finance manager: clears the exceptions. Moved assets are updated to their new location. Not-found and damaged assets are investigated and, where confirmed, recorded as disposals.
- Finance manager: closes the year. Depreciation journals go to the accounting system, and the verification report and both books' figures go to the auditors and to the team preparing the deferred tax working.
The depreciation explained video walks through all of this on a demonstration company, problem by problem and book by book: classes and rates, the cutover from Excel, the monthly close with extra shift depreciation, components, the 180-day rule, sales and section 50, impairment and leases, and the year end.
Before and after
| Before | With Asset Infinity | |
|---|---|---|
| Fixed asset register | An Excel workbook | One register with location and custodian |
| Book and tax depreciation | Two workbooks that drift apart | Both calculated from the same assets |
| Additions and disposals | Keyed twice | Entered once |
| Physical verification | Printed lists and ticks | Mobile scans with statuses |
| Moved assets | Left at the old location | Updated during the round |
| Audit evidence | Hard to produce | Reports from the register |
The first month
- Register imported. The spreadsheet register was imported with cost, date put to use, Schedule II class and tax block for each asset.
- Opening balances loaded for each book. The Companies Act book took each asset’s depreciation to date from the audited register, and the Income-tax book took each block’s written-down value from the tax audit report. Every line was checked before anything was written, and lines that could not be placed were named with the reason.
- Opening values reconciled. The first depreciation run was checked against both workbooks before they were retired.
- Assets labeled. Each plant labeled its assets with QR tags, ready for the year-end verification round.
The register format and the columns each book needs are set out in how to prepare a fixed asset register, with a template to download, and the count itself in physical verification of assets. The same register runs every other part of fixed asset management software in Asset Infinity.
Example results
- 2 depreciation books, Companies Act and Income-tax, from one register
- Every asset counted in a verification round before year end
- Every exception from verification followed up before the books close
- Additions and disposals are entered once and flow to both book and tax depreciation.
- Verification results come back as statuses on the register, not ticks on paper.
- Assets found at another plant are updated to their new location during the round.
- Auditors receive the verification report and depreciation schedules from the same register.
Why it worked
One register, two laws
Book and tax depreciation come from the same asset records, so they cannot disagree about what the company owns.
Verification that updates the books
Each scan sets a status on the register, so exceptions are followed up in the same place the books are kept.
Ready for the auditors
Schedules and verification reports are drawn from one source, with an audit trail behind every change.
Looking ahead
With one register serving both the Companies Act and the Income-tax Act, and verification recorded in the mobile app, the company closes its fixed asset books without reconciling separate workbooks.
The same register also holds each asset’s location, custodian and maintenance history, so finance and operations work from one list of what the company owns.