

Depreciation in India Explained: Companies Act vs Income-tax Act
Every company in India keeps two depreciation books for the same assets: one under Schedule II of the Companies Act, 2013 for its accounts, and one under the Income-tax Act for its return. The two never agree. This video takes the subject one problem at a time: what goes wrong, what each law asks for, and how Asset Infinity handles it in each book. It is shown on a demonstration company, a film manufacturer with two plants, a warehouse and a head office.
What you’ll see:
- One machine depreciated both ways: straight line over its useful life against written-down value at the block rate
- Schedule II classes and lives beside the Income-tax blocks and rates, set up once for the same company
- Opening balances loaded from the audited register and the tax audit report, checked line by line
- A month calculated and posted in the Companies Act book, with extra shift depreciation taken from the hour meter
- A production line carried as components, each on its own life
- Income-tax blocks, the 180-day rule and a sale that empties a block under section 50
- An impairment, a changed useful life, a leased office and a capital project in the Companies Act book only
- Journals for the general ledger, and the block-wise working for the tax return
The rates and rules shown are the common ones; confirm them for your company with your auditor. To see both books on one register for your own assets, book a demo, or read how an Indian company runs Companies Act and tax depreciation.
Transcript
Introduction
Depreciation is one of the least understood parts of a company's books in India. Every company keeps two depreciation books for the same assets — one under the Companies Act, 2013, and one under the Income-tax Act, 1961 — and the two never agree. In this video we take it one problem at a time: what the problem is, what each law actually asks for, and how Asset Infinity handles it, book by book. Our example is Vasundhara Polyfilms: two film plants, a warehouse and a head office, with eighty-six assets.
One machine, two answers
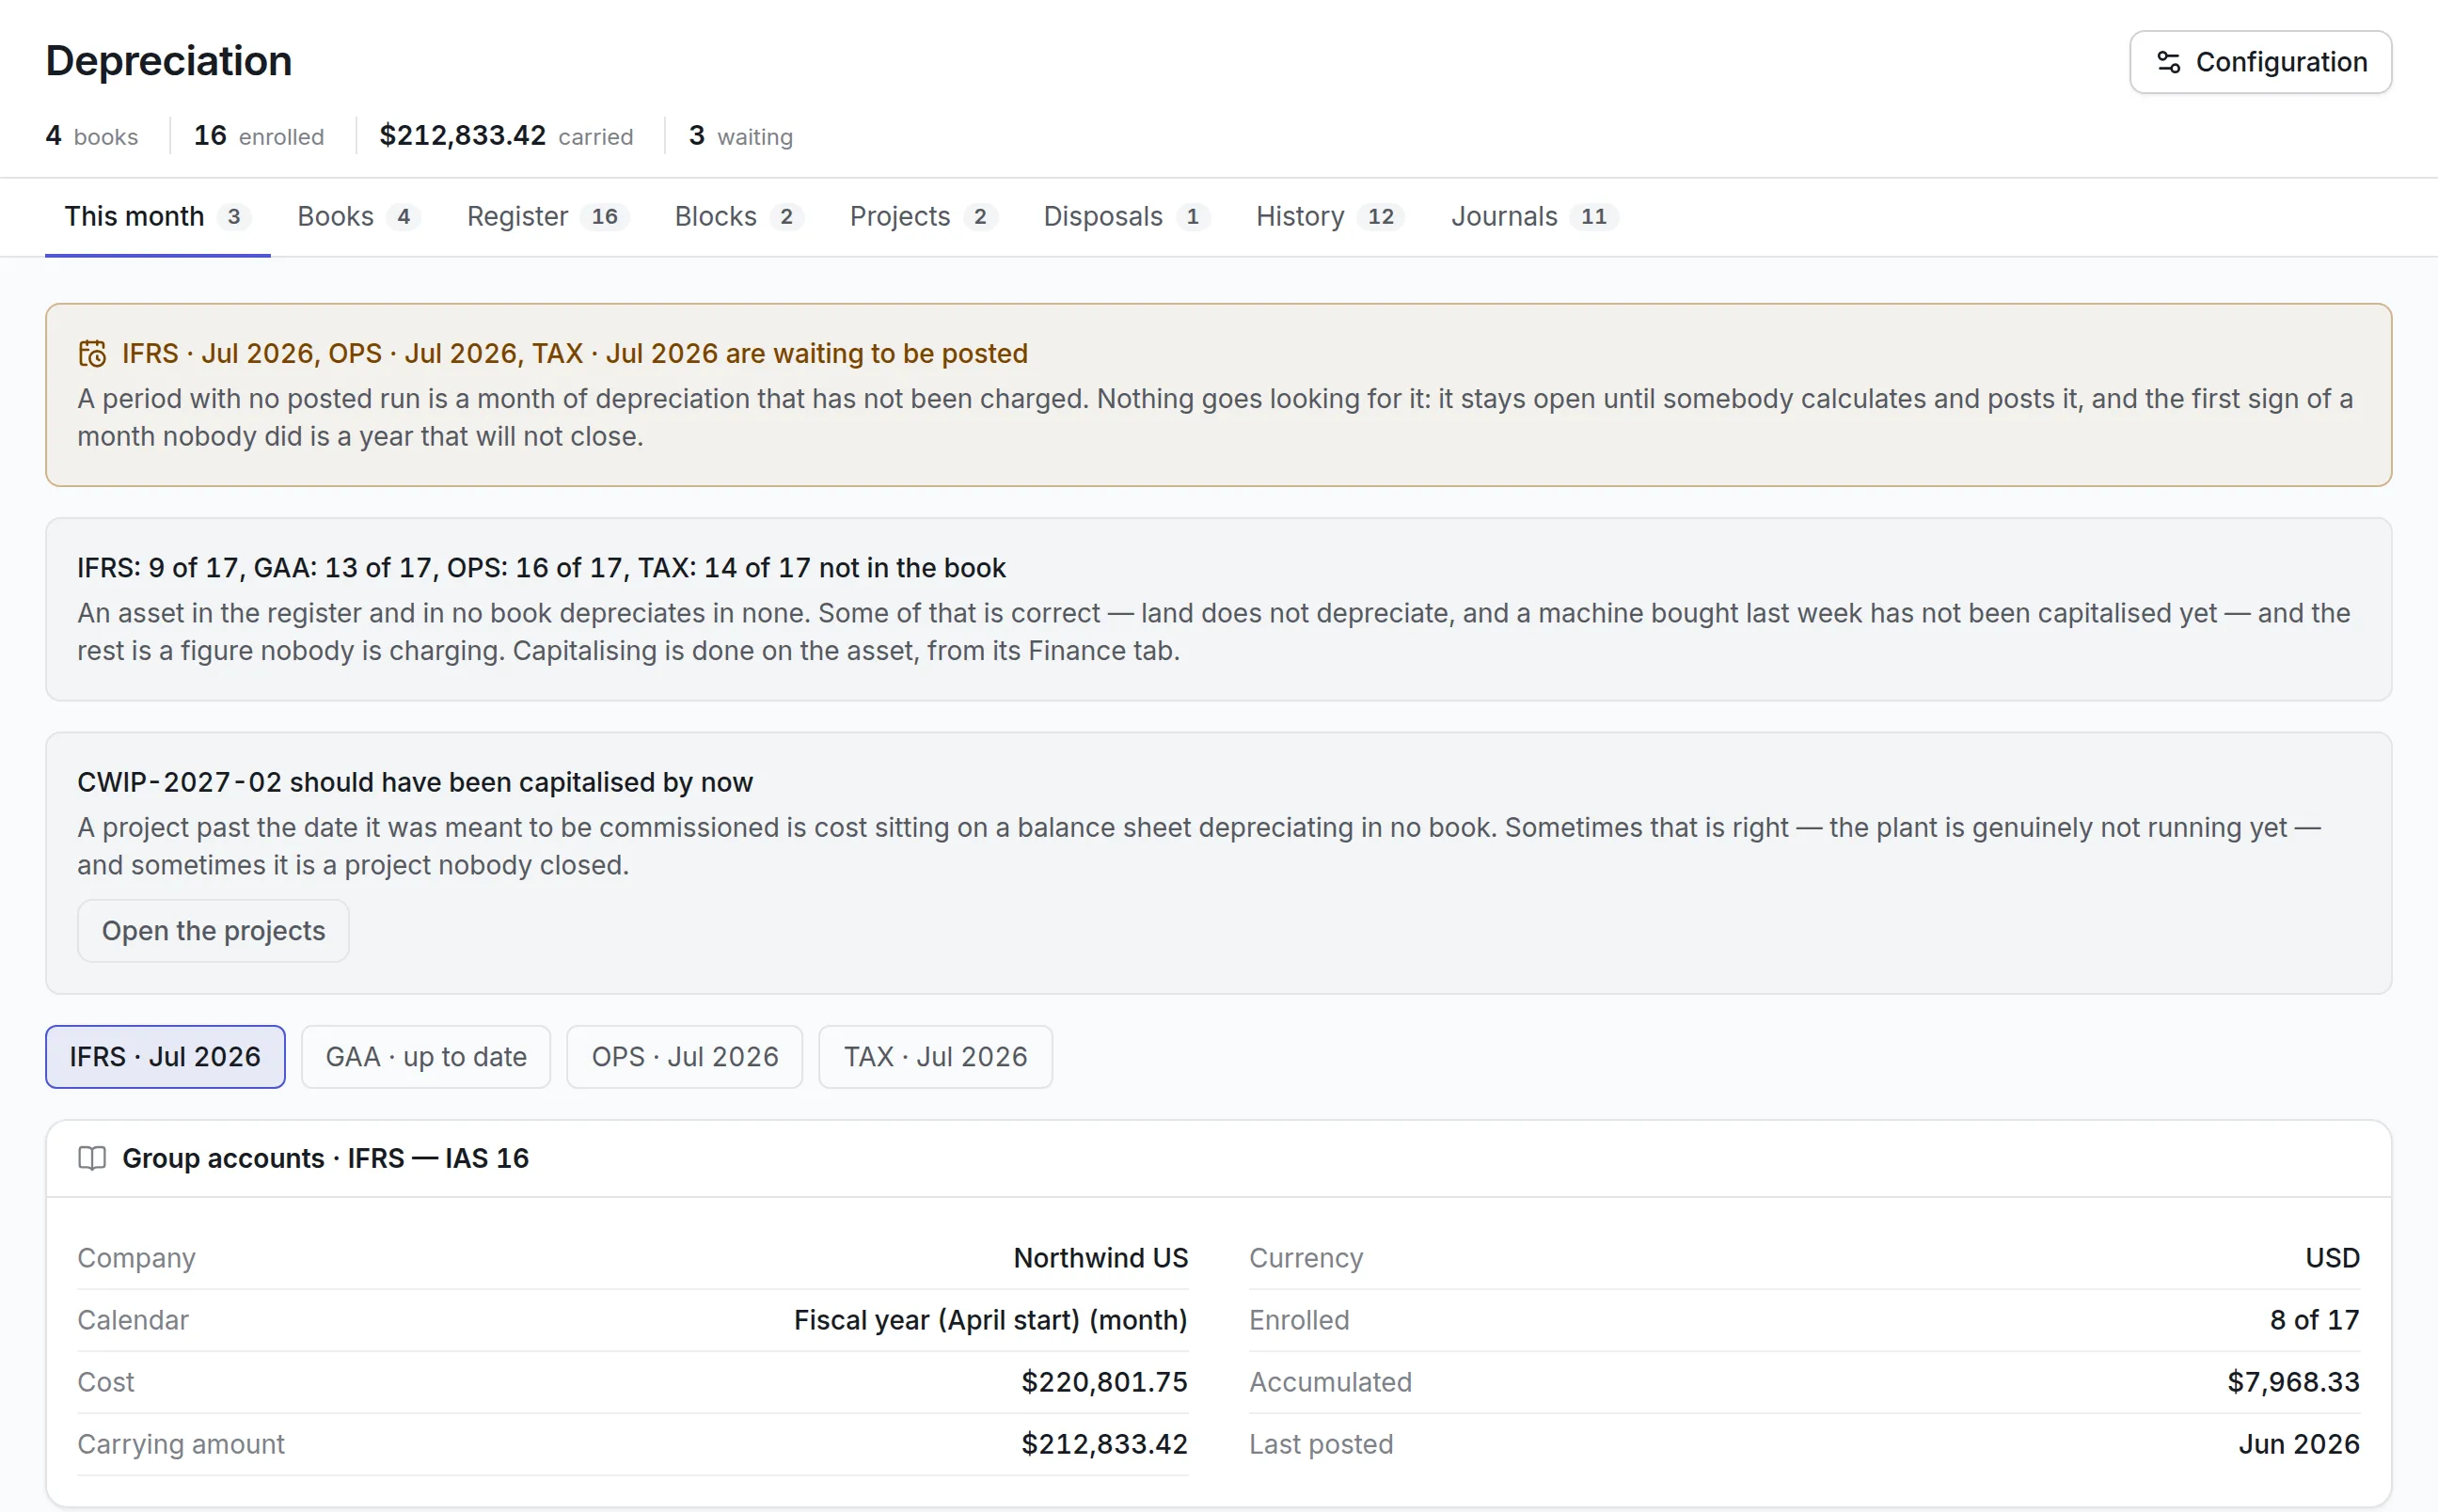
First, why two books at all? Take one machine that cost ₹10 lakh. The Companies Act book, under Schedule II, spreads its cost evenly over its useful life: fifteen years for plant and machinery, keeping up to five percent as residual value. That's ₹63,333 a year — the same every year. The Income-tax book uses written-down value instead: fifteen percent of whatever is left. That's ₹1,50,000 in the first year, ₹1,27,500 in the second, and a little less every year after. Neither figure is wrong. The first gives shareholders a true and fair value; the second is the deduction the tax law allows. A company has to keep both, and explain the difference. Kavita is Vasundhara's CFO. Let's sign in as her. The depreciation screen opens on what needs doing. Two books: the Companies Act book and the Income-tax book. One hundred and sixty-six enrolments — each asset counted once in every book it belongs to. ₹227 crore carried in the accounts. And two runs waiting: September in the Companies Act book, and this year's computation in the Income-tax book.
Two books that never agree
Problem one. The two books are kept in two different spreadsheets, on two different ways of classifying the same assets, and over time they drift apart. Here's what each law asks for. The Companies Act book groups assets by useful life, from Part C of Schedule II: thirty years for a factory building, fifteen for plant and machinery, twenty-five for a continuous process plant, three years for a laptop and six for a server. The residual value is normally no more than five percent of cost; a company may use a higher figure only if it justifies it and discloses why. The Income-tax book groups the same assets into blocks by rate, from Appendix I: ten percent for buildings and five for residential ones, fifteen for plant and machinery, forty for computers, pollution control equipment and solar, twenty-five for intangible assets. There's no residual: a block keeps depreciating towards zero. Here's how Asset Infinity solves it. Both books are set up once, for the same company. The Companies Act book is run every month; the Income-tax book is run once a year. Below them are the classes. The Companies Act classes carry Schedule II's useful lives — twenty-five years for the continuous process plant. The Income-tax blocks carry their rates — fifteen percent for plant and machinery. Then the policies. In the Companies Act book: straight line, and Vasundhara keeps the usual five percent residual. In the Income-tax book: written-down value, no residual, and the hundred-and-eighty-day rule built in. Every asset carries both answers on one screen. This is the metallizer at Shendra. In the Companies Act book it stands at ₹4.16 crore: twenty-four and a half crore of cost, less what fifteen years' straight line has charged so far. In the Income-tax book there is no figure for this machine on its own. It sits in the fifteen percent plant and machinery block, and the block has one written-down value for everything inside it. The screen says so, instead of inventing a number.
Years of history in Excel
Problem two. Years of history sit in an Excel register and in last year's tax audit report, and moving to a system usually means typing all of it in again. Each book starts from a different kind of history. The Companies Act book needs, for every single asset, its cost, the date it was put to use, and the depreciation already charged. That comes from the audited fixed asset register. The Income-tax book needs the written-down value of each block on the first day of the year. That comes from the tax audit report: Form 3CD, clause 18. Here's how Asset Infinity solves it. Vasundhara moved across on the first of April 2025. For the Companies Act book, the audited register was loaded here: one line per asset, with its cost, the date it went into use, and what had already been charged. Every line is checked against the register before anything is written. Seventy-one lines went in. One was blocked: a compressor scrapped in 2023 that the old spreadsheet still carried — named, with the reason, instead of loaded. The summary at the top shows the result: seventy-one applied, one blocked, nothing left waiting. And every applied line becomes a dated entry on the asset, with its source and who recorded it, so an opening figure can always be traced back to the register. Now switch to the Income-tax book. The same assets, loaded with what the tax audit report says. Look at the effluent treatment plant. It cost ₹1.60 crore, and the tax book has nothing left of it: pollution control equipment was written off at a hundred percent in the year it was bought. In the Companies Act book, the same plant is still carried at ₹58 lakh. The two books disagree from day one, and the system keeps both.
A month-end nobody can explain
Problem three. The accounts need a depreciation charge every month. It's usually worked out in a spreadsheet, and nobody can show how a figure was arrived at. Here the two laws work very differently. The Companies Act book is charged every month: cost less residual, divided by the useful life, from the date the asset was put to use. And Schedule II has a rule many teams miss. If a machine works a double shift in a period, its depreciation for that period goes up by fifty percent; a triple shift, by a hundred percent. Assets marked NESD — no extra shift depreciation, like a continuous process plant — never get the increase. The Income-tax book has no monthly charge and no shift rule at all. Tax depreciation is worked out once, for the whole year. Here's how Asset Infinity solves it, in the Companies Act book. September has been calculated and is waiting for the controller to post it: seventy assets charged, ₹1.71 crore in all. Fifteen assets were not charged, and their reasons come first. Some are already at their five percent residual. Some have been sold. And a fire detection system was handed over without an invoice, so it has no cost yet — a line to chase, not a silent zero. Below them, every charge, with its working. The metallizer cost twenty-four and a half crore. Less its five percent residual, spread over a hundred and eighty months, that's about ₹12.9 lakh a month. In September it ran a double shift — measured from its own hour meter, against the plant's working week — so the charge goes up by half, to ₹19.4 lakh. The film lines are continuous process plant, so they get no increase however long they run. Every month is kept: seventeen posted so far, each with its journal. And there's a control built in. The fixed asset accountant can calculate a month, but only the financial controller can post it or reverse it.
One line, many lives
Problem four. A big production line is really many assets, each with its own useful life. This one is specific to the Companies Act. Schedule II requires component accounting: when a significant part of an asset has a different useful life, that part is depreciated separately. The Income-tax Act has no such idea. The whole cost of the line simply goes into the fifteen percent plant and machinery block. Here's how Asset Infinity solves it. Line one is carried as four components: the extruder, the stretching frame, the winder, and the control system. Each has its own schedule in the Companies Act book. The control system has a ten-year life on a twenty-five-year line, so it reached its residual back in 2022, while the rest of the line runs on. Here are the same parts in the register, each on its own line in the Companies Act book, with its own cost, depreciation to date and carrying amount. The extruder cost ₹28.4 crore and is still carried at ₹13.3 crore. The stretching frame and the winder are the same age and keep depreciating at the same pace. The control system has stopped at its five percent residual of ₹21 lakh — and that doesn't stop the rest of the line. On the line's Finance tab, the parts are added up. In the Companies Act book, line one and its parts are worth ₹43 crore together. In the Income-tax book, the same cost sits inside the plant and machinery block, as one figure with everything else.
Tax works on blocks, not machines
Problem five. For tax, depreciation isn't worked out machine by machine, and a purchase late in the year changes the answer. This one is specific to the Income-tax Act. Assets are pooled into blocks. Each year, the block's opening written-down value, plus additions, less the sale price of anything sold, is depreciated at the block's rate. Then comes the hundred-and-eighty-day rule: an asset put to use for less than a hundred and eighty days in the year gets only half the rate that year. The other half isn't lost; it stays in the block for the years that follow. And a company in the twenty-two percent tax regime, under section 115BAA, can't claim additional depreciation. In the Companies Act book none of this applies: every asset has its own value, and a late purchase is simply charged for the days it was in use. Here's how Asset Infinity solves it, in the Income-tax book. Last year, the plant and machinery block opened at ₹86 crore. Slitter three came in during June — a full year's use — so it gets the full fifteen percent. The truck's sale price of four and a half lakh came straight off the block. Then the late additions: the spectrometer, the pool car and two forklifts were put to use with fewer than a hundred and eighty days of the year left, so they get half — seven and a half percent. Together, ₹13.7 crore of tax depreciation, and the block closes the year at ₹78 crore — which is exactly where this year opens. The forty percent block shows the rule at its sharpest. The rooftop solar plant went into use on the second of October — a hundred and eighty-one days before the year end, one more than it needed — so it got the full forty percent. The effluent upgrade came in January and got twenty.
One sale, two answers
Problem six. When an asset is sold, the two books give two completely different answers, and teams often post the wrong one. In the Companies Act book, a sale gives a profit or a loss: the sale price, less the asset's carrying amount, goes to the profit and loss account. In the Income-tax book, there is no profit or loss on a single asset. The sale price is simply taken off the block. Only if the sale price is more than the whole block is there a gain — and then it's treated as a short-term capital gain, under section 50. Here's how Asset Infinity solves it. Four assets left this year. Each sale is recorded once, and each book draws its own conclusion. The truck was sold for four and a half lakh. In the Companies Act book it was carried at ₹1.1 lakh, so that's a gain of ₹3.4 lakh. In the Income-tax book, the four and a half lakh simply reduced the plant block. The trademark is the interesting one. It was sold for ₹2.40 crore. In the Companies Act book it was carried at seventy-three and a half lakh, so the gain is ₹1.66 crore. In the Income-tax book it was in the intangibles block, and the sale price simply came off that block. But that block only had ₹1.33 crore in it. The sale price emptied it completely. No depreciation is due on the block this year, and the excess — ₹1.07 crore — is a short-term capital gain under section 50, recorded here for the tax return.
Judgements the auditor tests
Problem seven. Impairments, changes in useful life, leases and assets under construction all need judgement — and the auditor tests every one. Vasundhara is a listed company, so its accounts follow Ind AS, and these rules live in its Companies Act book. A company on the older Indian accounting standards applies the same ideas under AS 10 and AS 28. An asset worth less than its carrying amount is written down, under Ind AS 36. A change in useful life applies from now on, never to the past, and is disclosed with the technical advice behind it. A leased office becomes a right-of-use asset, under Ind AS 116. And a plant under construction isn't depreciated until it's available for use. The Income-tax Act ignores impairments and changes of life — its rates are fixed — and lease rent is simply an expense. Only one rule is shared by both books: depreciation starts when the asset is put to use. Here's how Asset Infinity solves it. The coating line lost its largest customer. It was tested at the year end and written down by ₹1.75 crore — in the Companies Act book only. The Income-tax book carries on as if nothing had happened. The Silvassa forklifts run three shifts, and the manufacturer's technical assessment put their life at ten years instead of fifteen. The change applies from April, nothing already posted is restated, and the reason is kept for the disclosure in the accounts. The head office is leased for nine years. In the Companies Act book, it's a right-of-use asset of ₹5.4 crore, depreciated over the lease term. In the Income-tax book it doesn't appear at all — the rent is simply an expense. And the second metallizer was built as a project: its costs were gathered for nine months with nothing depreciated, then it was capitalised in August as two assets — the machine and its transformer. Line three is still being built: ₹41 crore of capital work in progress, which won't be depreciated until it's available for use.
Closing the year
Problem eight. At the year end both books have to be closed: the accounts need their journals, and the return needs the block-wise working. In the Companies Act book, depreciation is posted to the general ledger, and the fixed asset note in the accounts is built from it. In the Income-tax book, the block-wise working goes into the tax audit report and the return. Here's how Asset Infinity solves it. Every posted month in the Companies Act book becomes a balanced journal — debits always equal credits — by account and cost centre, and every sale gets a journal of its own. Asset Infinity is the fixed asset subledger, so it doesn't post into your general ledger directly: each journal is sent to your accounting system through a connector, or downloaded and imported. August's is ready to send; the months before it have already gone. And posting a month is a controlled step: only the financial controller can do it. Two books, one register, and every figure with its working. If your team still keeps depreciation in spreadsheets, see it with your own assets: book a demo, or start a free trial at assetinfinity.com.
See it with your own assets
A demo run on an example from your industry. Or start the trial and look around on your own.